
How to choose a place to live in Dubai: tips on areas, budget, and rental conditions
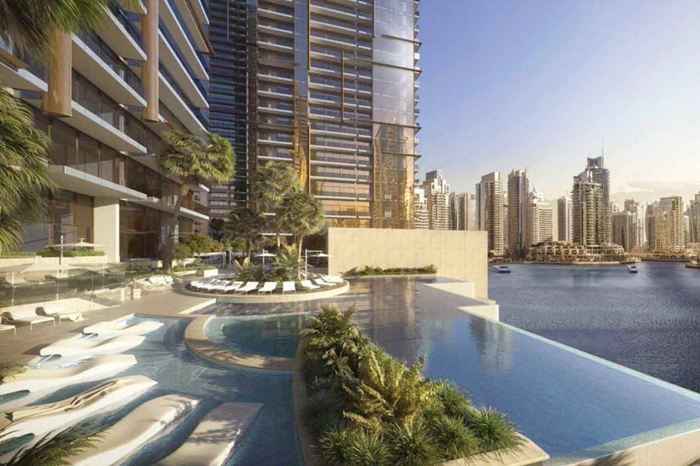
Selecting a property in Dubai begins with determining the purpose of purchasing or renting: for personal residence, investment, or short-term use. It’s important to evaluate the area in advance, considering transportation accessibility, proximity to work and schools, infrastructure, and noise levels.
It’s also important to consider lifestyle and property type – from apartments in high-rise complexes to villas in gated communities – taking into account the specifics market real estate in dubai.
Before making a decision, carefully compare property types by size, layout, quality of finishes, and amenities, clarify building maintenance terms, and any additional regular fees. It’s equally important to check the legal aspects of the transaction, the reputation of the developer or landlord, and realistic delivery times to ensure the chosen property meets your budget, expectations, and long-term plans.
Checking Title through the Dubai Land Department: Steps to Follow Before Payment
Before paying for your chosen property in Dubai, it’s important to ensure the seller holds the title and that the property is free of encumbrances. The basic verification logic is simple: you verify information from the official Dubai Land Department (DLD) system with the seller’s documents and transaction terms, and then secure the payment process.
Even if you’re purchasing a home through an agent or developer, independently verifying your property through DLD reduces the risk of document substitution, hidden liens, restrictions on property ownership, or unauthorized attempts to sell the property. Below are practical steps to take before making a deposit and especially before the final payment.
Step-by-step steps through DLD before making a deposit
- Ask the seller for a set of property identifiers. You’ll need information that clearly identifies the property in the registry: the Title Deed (certificate of ownership) or the property/plot number (e.g., plot/unit), as well as the exact name of the project/tower and district.
- Check the Title Deed data against the information in DLD. When checking, ensure that the owner’s name, unit number, project, area, and other key details match. If the transaction is being conducted through a representative, verify that there is a valid basis for representation (power of attorney/authorization) and that it specifically covers the right to sell.
- Check for encumbrances and restrictions. It is important to determine whether there are any mortgages, liens, legal disputes, or other restrictions that restrict the registration of the transfer of title. If there is a mortgage, agree on the closure mechanism in advance: when and with what funds the encumbrance will be removed, and what confirmations you will receive before the principal payment is transferred.
- Check the status of the property: completed or under construction (off-plan). For properties under construction, verify that the project is registered and payments are made strictly according to the approved scheme and to the correct bank details. For completed housing, it’s important to ensure that the property is already occupied and can be transferred to the new owner without any additional obstacles.
- Check that you are paying the correct party and for the correct reasons. Before paying the deposit, ensure that the documents clearly state to whom the funds are being transferred and for what purpose, under what conditions the deposit will be returned, and what will be considered confirmation of the successful registration of the transaction.
- Agree on a secure payment procedure. It’s generally safer to link large payments to the event of registering the transfer of title in the DLD, rather than to verbal promises. Clarify what supporting documents you will receive after registration, and who is responsible for submitting/supporting the registration.
Checkpoints before the final transfer and common mistakes
- Checkpoint #1: Data relevance. Conduct a final reconciliation immediately before signing/submitting for registration: information about the owner and encumbrances must be current as of the transaction date.
- Checkpoint #2: Matching the parties in the documents. The seller’s name in the contract must match the owner in the register; if a representative signs, the authority must be verifiable and sufficient.
- Checkpoint #3: No «payment before verification.» Do not transfer significant amounts until ownership and the absence of blocking restrictions have been confirmed.
- Common mistake: Relying solely on scans. A Title Deed scan without verification against official data does not protect against counterfeiting and outdated information.
- Common mistake: Ignoring the mortgage. The presence of a mortgage does not always prohibit the transaction, but it requires a clear scenario for removing the encumbrance and documentary evidence before full payment.
- Common mistake: Vague deposit terms. If you don’t specify that the deposit will be returned if any discrepancies are discovered (such as encumbrances or lack of authority), you risk losing money even if the problem is obvious.
Hello!! My name is Jeanine
I love to eat, travel, and eat some more! I am married to the man of my dreams and have a beautiful little girl whose smiles can brighten anyone’s day!